
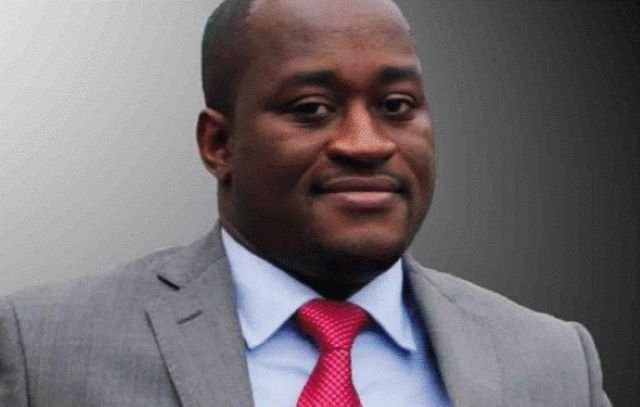

Dr Theo Acheampong, Technical Adviser to the Ministry of Finance, has defended the government’s 24-Hour Economy programme amid questions about its ability to deliver the promised employment opportunities.
According to him, some jobs have already been created, but he acknowledged that more work is needed to create more.
Speaking on TV3’s The Key Points during a discussion of the 2027 Budget on Saturday, November 2024, Dr Acheampong was challenged over concerns that the programme had not delivered the expected number of jobs nearly two years after its introduction.
Also read: $10bn New Economy plan keeps changing; Oppong Nkrumah cites shifting figures
Dr Theo Acheampong argued that the programme has contributed to job creation, although he acknowledged that the government must do more to expand employment opportunities.
“Some jobs have been created. I can point to some,” he said.
He explained that the government’s employment strategy is designed around mobilising private-sector investment, with the government providing the necessary incentives and support to stimulate business expansion.
According to him, the original 24-Hour Economy framework envisaged mobilising about $4 billion, with the largest portion expected to come from private-sector capital rather than direct government expenditure.
Government, he said, intended to support participating businesses through incentives, including tax waivers, import duty exemptions, relief on the National Health Insurance Levy (NHIL) and accelerated depreciation allowances.
Dr Acheampong explained that these incentives are intended to reduce the cost of investment and encourage businesses to expand their operations, creating more sustainable employment opportunities.
He maintained that macroeconomic stability is a critical foundation for the successful implementation of the 24-Hour Economy.
According to him, the government has prioritised restoring economic stability before moving towards expanding private-sector activity, particularly among small and medium-sized enterprises.
Dr Theo Acheampong noted that although inflation has declined and economic growth has improved, the cost of credit remains relatively high, limiting the ability of businesses to borrow, expand and employ more people.
The government’s next priority, he said, is to reduce borrowing costs and improve access to affordable financing to enable businesses to create sustainable and decent jobs.