
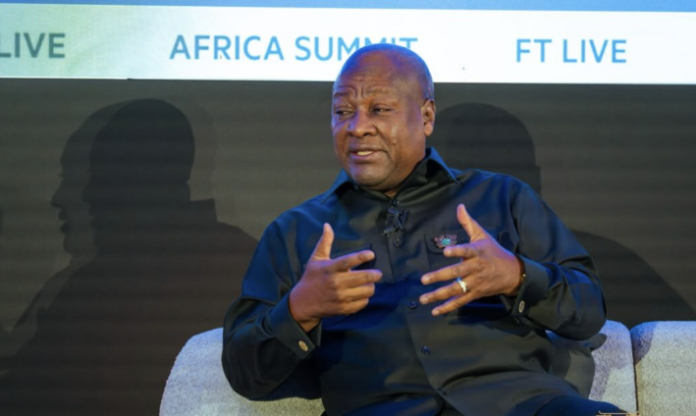

President John Dramani Mahama has touted his administration’s $10 billion Big Push Infrastructure Programme, saying the initiative will accelerate infrastructure development, create hundreds of thousands of jobs and complete stalled legacy projects across the country.
Speaking at the 13th Financial Times (FT) Africa Summit in London, President Mahama said the programme would be implemented over five years, with $2 billion allocated annually.
“We are building infrastructure through the Big Push Programme. It is a $10 billion programme over five years, with $2 billion allocated each year,” he said.
Also read: MPs urged to respond promptly to journalists to strengthen balanced reporting
He explained that the programme, which began with road infrastructure, would expand to cover schools, hospitals, irrigation schemes, and other projects to support national development.
President Mahama also announced plans for a new economy plan involving $10 billion in self-financed investment over four years. He said the funds would go to nine job-rich sectors, including tourism, energy, agriculture, agro-processing, pharmaceuticals, and textiles and garments.
He attributed the planned investments to fiscal adjustments his administration is undertaking, including reducing the primary balance target agreed with the International Monetary Fund (IMF) from 1.5 per cent to 0.5 per cent.
The President said the adjustment would create an additional fiscal space equivalent to one percentage point, which would be channelled into the targeted sectors to stimulate economic activity and employment.
“However, the economy is holding steadily. Our currency is stable, and interest rates are still falling. I think there is a lot we can do for ourselves, even as we call for reform of the global order,” he said.
The two-day summit, held under the theme “Mobilising Growth in a New Global Order”, brought together global business leaders, policymakers and heads of state to discuss economic growth and development.
Addressing Africa’s debt burden and the global financial system, President Mahama argued that the international economic order placed the continent at a disadvantage, particularly in accessing financing to respond to climate change.
“We contribute just four per cent of greenhouse gas emissions, yet we borrow at eight times the cost to deal with the effects of flooding, forest fires and other climate-related challenges,” he said.
He further cited the financial resources leaving the continent through debt servicing and illicit financial flows, saying about $80 billion went out annually in interest and debt repayments, while another $90 billion was lost through illicit financial flows, transfer pricing and related practices.
The President also expressed concern about declining Overseas Development Assistance (ODA), noting that it fell by 23.5 per cent in 2025 and was expected to decline further in 2026.
Despite these challenges, he described Africa as resilient, arguing that the continent continued to endure substantial financial outflows even as development assistance dwindled.
“More than $200 billion goes out every year while ODA continues to dwindle,” he said, questioning how Europe would have coped under similar circumstances.
Myjoyonline